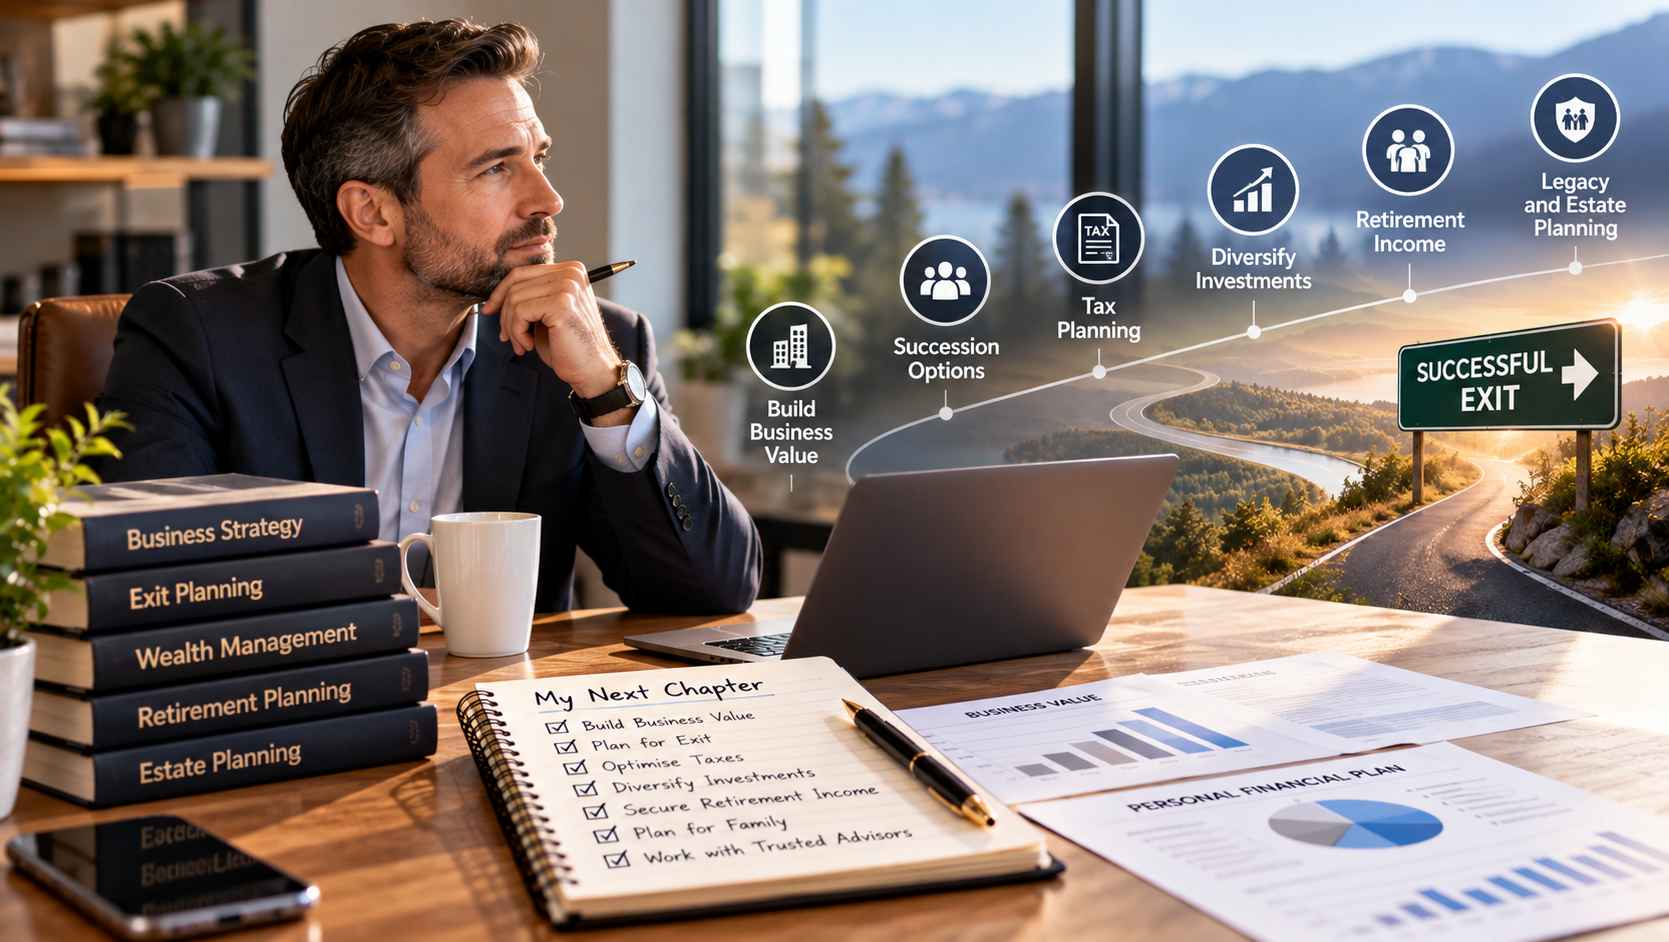
For an entrepreneur, the business and personal balance sheet can become closely connected. The company may provide income, fund family goals, support retirement savings, and represent the largest asset the owner expects to have.
That connection can create a planning challenge when the owner eventually wants to sell, transfer, or step away from the business. A successful exit may create substantial liquidity, but the timing, value, tax consequences, and structure of a transaction are not guaranteed.
That is why exit planning should include more than preparing the company for a buyer. It should also examine whether the owner’s personal finances are prepared for life after the business.
Why Exit Planning Should Begin Early
Business exits rarely happen in isolation. An owner may have a preferred retirement date, family commitments, estate objectives, debt, investment goals, or plans for a second career.
Starting the conversation early gives the owner more time to identify gaps.
For example, someone who expects the business to fund most of their retirement may discover that personal savings and investments are relatively limited outside the company. Another owner may have enough assets overall but too much wealth concentrated in the business itself.
Exponent Investment Management works with professionals, business owners, and families on wealth and financial planning considerations that can connect personal financial goals with longer-term decisions.
The purpose of planning is not to predict exactly what an eventual sale will produce. It is to understand the range of possible outcomes and prepare for them.
Separate Business Wealth From Personal Financial Needs
A business can be valuable without being the same thing as personal financial security.
Owners often reinvest profits into operations, property, equipment, hiring, or expansion. Those decisions may support the company’s growth, but they can also leave the owner’s personal wealth heavily concentrated in one asset.
This concentration matters when an exit is approaching.
A business sale may take longer than expected. A buyer may require financing or a transition period. The owner may decide to transfer the company to family members or existing employees instead of selling outright.
Each path can affect when and how personal wealth becomes available.
Building personal assets outside the company can provide another layer of flexibility. The appropriate mix will depend on the owner’s circumstances, risk tolerance, time horizon, and goals, so this is an area where individualized professional advice can be valuable.
Think About Retirement Income, Not Just a Sale Price
It is easy to focus on a future business valuation and overlook what happens after the transaction.
Retirement planning is ultimately about sustainable income and spending, not simply reaching a particular asset value.
An owner can begin by estimating the lifestyle they want after leaving the business. Housing, travel, healthcare, family support, taxes, insurance, and other expenses can all affect the amount of income required.
The Government of Canada’s retirement planning guidance emphasizes considering expected spending, retirement timing, sources of income, and personal savings when preparing for retirement.
The eventual business proceeds may be one source of retirement capital, but they may sit alongside registered savings, investments, pensions, government benefits, and other assets.
Looking at those sources together can provide a more complete picture of what life after the business might look like.
Consider Taxes and Estate Planning
The financial result of an exit is affected by more than the headline transaction value.
The structure of the sale, ownership arrangements, applicable tax rules, and the timing of transactions can all influence what ultimately becomes available to the owner and family.
Tax planning should therefore be considered before a transaction is underway rather than treated as an administrative task at the end.
Estate planning is another important part of the conversation.
Business owners may need to consider what happens if they die before an intended sale, become unable to manage the business, or transfer ownership to family members. A will, powers of attorney, ownership documents, insurance arrangements, and other estate-planning tools may need to work together.
The exact legal and tax requirements vary by situation and jurisdiction, so owners should involve qualified legal and tax professionals rather than relying on a general template.
Diversification Before an Exit
Diversification can be particularly important for owners whose net worth is dominated by their company.
Selling a business can suddenly convert a concentrated business asset into cash or an investment portfolio. That transition can change the owner’s risk profile dramatically.
However, diversification does not necessarily mean making a large investment change immediately before an exit.
It can be a gradual process of building personal investments over time, reviewing existing assets, managing debt, and considering how much exposure the family can reasonably have to the business.
The earlier this conversation begins, the more options an owner may have.
A long planning horizon can make it easier to consider different scenarios without making decisions solely because an exit is approaching.
Preparing for Different Exit Scenarios
There is rarely only one possible way to leave a business.
An owner might:
- Sell to another company or entrepreneur
- Transfer ownership to family
- Sell to employees or existing partners
- Gradually reduce their involvement
- Retain an ownership interest while stepping back from daily operations
- Continue operating the business longer than originally expected
Each scenario can produce a different financial and personal outcome.
Government of Canada guidance on business succession planning recognizes that ownership transitions can involve selling a business or transferring ownership to relatives or other entrepreneurs.
Thinking through several scenarios can help reveal questions that might otherwise be overlooked.
For example, if a family transfer produces less immediate liquidity than an external sale, the owner’s retirement plan may need to account for that difference. If the owner remains involved after a sale, their expected income and timeline may also change.
Scenario planning is therefore useful even when the final exit strategy has not been selected.
Working With Professional Advisors
Preparing for a business exit is usually not a single-advisor exercise.
The business owner may need input from a financial planner or wealth advisor, accountant, tax professional, lawyer, business valuation specialist, and other professionals depending on the situation.
The important part is coordination.
A business decision can have personal financial consequences, just as a personal estate or retirement decision can affect the business.
A coordinated approach to financial planning for business owners can help connect questions such as:
- What does the owner want life after the business to look like?
- How much personal income may be needed?
- How much wealth is currently tied to the company?
- What happens if the business is sold for less than expected?
- What happens if the owner exits earlier than planned?
- How might taxes affect the assets available after a transaction?
- How should assets be structured for family and estate objectives?
These are planning questions rather than predictions. Their value comes from helping the owner understand trade-offs before decisions become urgent.
Build Personal Flexibility Before the Exit
A business exit is both a corporate event and a personal financial transition.
Preparing only the company can leave an owner with a polished succession plan but an unclear picture of what comes next. Preparing only personal investments can overlook the value, structure, and risks tied to the business itself.
A stronger approach considers both sides together.
Business owners do not need to know exactly when they will exit or precisely what the business will be worth years in advance. They can instead work toward greater financial flexibility by building personal wealth outside the company, understanding retirement income needs, reviewing tax and estate considerations, and considering several possible transition paths.
The earlier those conversations begin, the more opportunity there is to make thoughtful decisions rather than trying to solve every financial question at the moment an exit becomes imminent.


